NEWSLETTER
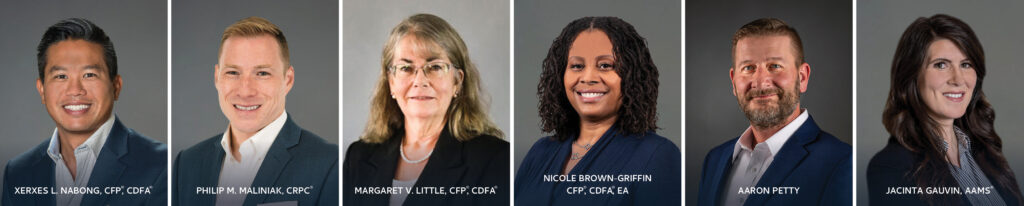
Xerxes Nabong, CFP®, CDFA®
Philip M. Maliniak, CRPC®
Nicole Brown-Griffin, CFP®, CDFA®, EA
Aaron Petty, Client Associate
Hampton Roads: (757) 394-3486
Greater Phoenix: (480) 687-9339
Orange County: (949) 660-8869
Wealth Avenue October 2026 Newsletter: Insurance 101: Protecting What Matters Most
A strong financial plan is not only about growing your wealth. It is also about protecting your income, your family, and everything you have worked hard to build.
When it comes to risk, you generally have three choices: absorb it, manage it, or transfer it. Smaller risks may be absorbed through savings or cash flow. Other risks can be managed by changing behavior, improving safety, or putting the proper legal and planning documents in place. When the potential financial impact is too great to comfortably carry on your own, that risk may be transferred to an insurance company.
That is where thoughtful insurance planning becomes important. The best insurance plan is not necessarily the one with the most coverage… it is the one designed around your life, budget, responsibilities, and long-term goals.
Coverage Through Work: A Good Starting Point
Many employers offer life and disability insurance as part of their benefits package. This coverage is often affordable and easy to obtain, but it may not be enough and it may not follow you when you change jobs or retire.
Some plans offer portability or conversion options, but they may be limited, more expensive, and timesensitive. Individually owned coverage generally stays with you regardless of where you work and can be designed around your specific needs, subject to underwriting and policy approval.
Employer-provided coverage may also be tied to your compensation, employment status, or benefit elections. Review your plan documents carefully so you understand what is covered, when coverage ends, and what options may be available if your employment changes.
Questions to Ask: If I left my employer tomorrow, what coverage would I lose? Would my family still have enough protection if my benefits ended, changed, or became too expensive to keep?
Disability Insurance: Protecting Your Income
Your ability to earn an income may be one of your most valuable assets. Disability insurance replaces a portion of your income if an illness or injury prevents you from working.
One way to think about disability coverage is to look beyond a single paycheck. For example, someone planning to work 20 more years at a $150,000 annual salary could expect to earn approximately $3 million in gross wages over that period, before considering raises, bonuses, taxes, inflation, or changes in employment. A long-term disability could affect not only current income, but also retirement savings, employer matching contributions, potential pension benefits, and future Social Security benefits tied to earnings history.
Short-term disability typically covers a limited period, while long-term disability may provide benefits for several years or even until retirement. Review the benefit amount, waiting period, benefit period, exclusions, limitations, and how the policy defines a disability.
Disability benefits may be taxable or tax-free depending on who pays the premium and how the policy is structured.
Questions to Ask: If a disability reduced my income by 40% to 60%, could we still afford to stay in our home, keep our children on track for college, and continue saving for retirement? Would we have to spend down emergency savings or retirement assets to cover day-to-day expenses or care costs?
Life Insurance: Protecting the People Who Depend on You
Life insurance can help replace lost income, pay debts, fund education, and provide financial stability for your family.
Term insurance provides coverage for a set number of years and is generally the more affordable option. It is often used to protect temporary needs, such as a mortgage or income-replacement period.
Permanent insurance is designed to remain in force for life, provided the policy is properly funded and policy requirements are met. It may also accumulate cash value, but it typically comes with higher premiums, fees, surrender charges, and greater complexity.
Cash value may grow tax-deferred, and policy loans or withdrawals may be available. However, loans and withdrawals can reduce the death benefit and cash value, may cause the policy to lapse, and may create tax consequences. Guarantees are based on the claims-paying ability of the issuing insurance company.
Neither type is automatically better. The right choice depends on why the coverage is needed, how long it is needed, affordability, health and insurability, and how it fits into your overall plan.
Questions to Ask: If I were no longer here, could my family afford to stay in our home, pay off or manage debt, keep the children on track for college, and maintain day-to-day stability? Would my spouse or family have enough time and financial breathing room to grieve, adjust, and make decisions without being forced into immediate financial changes?
Long-Term Care Insurance: Protecting Your Independence
Long-term care is not limited to nursing-home care. It may include assistance at home, in assisted living, or in a nursing facility when someone needs help with activities such as bathing, dressing, eating, or managing a cognitive impairment.
Coverage may come from a traditional long-term care policy or a life insurance policy with long-term care benefits. Important features include the monthly benefit, elimination period, length of coverage, inflation protection, benefit triggers, exclusions, and whether premiums may increase over time.
Long-term care insurance is subject to underwriting, and benefits are paid only if policy conditions are satisfied. Hybrid life insurance or annuity products with long-term care benefits may have additional costs, restrictions, and trade-offs compared with traditional coverage.
Questions to Ask: If I needed care for several years, would my family have to spend down savings, sell assets, or reduce their own retirement security to pay for it? Could the cost of my care affect any generational wealth I intend to pass on? Who would provide the care, and would that responsibility force a spouse or child to cut back at work, travel frequently, or take on a role they are not prepared for?
Auto Insurance: More Than Protecting Your Car
The value of your vehicle is only one part of the equation. Liability coverage protects you if you injure someone or damage their property. Uninsured and underinsured motorist coverage may help when the other driver has little or no insurance.
State-required minimums may not provide enough protection for someone with significant income or assets. Coverage availability, minimum requirements, deductibles, and exclusions vary by state and insurance carrier.
Questions to Ask: If I caused a serious accident, would my liability limits be enough to protect my home, savings, investments, and future income? If the other driver had little or no insurance, would my own coverage be enough to protect my family financially?
Homeowners Insurance: Focus on the Cost to Rebuild
Your home should generally be insured based on the cost to rebuild it, not simply its current market value. Homeowners insurance may also cover personal belongings, temporary living expenses, and personal liability.
Floods, earthquakes, water backup, jewelry, art, collectibles, business property, short-term rental activity, and other risks may require separate policies, riders, or endorsements. Policy limits, deductibles, exclusions, and claims procedures should be reviewed periodically.
Questions to Ask: If my home had to be rebuilt after a major loss, would my coverage reflect today’s construction costs, not just what I paid for the house or what it might sell for? Are valuable items, water damage, temporary housing, and liability risks covered the way I assume they are?
Umbrella Insurance: An Added Layer of Protection
An umbrella policy provides additional personal liability coverage above the limits of your auto and homeowners policies. It can help protect your savings, investments, property, and future income following a major accident or lawsuit.
Umbrella coverage generally requires certain underlying liability limits and may not cover every type of claim. Review policy exclusions carefully, especially for business activities, rental properties, intentional acts, or other specialized exposures.
Questions to Ask: If a lawsuit or major accident exceeded my home or auto liability limits, what assets and future income could be exposed? Would one unexpected event put my savings, investments, home equity, or retirement plans at risk?
Insurance Planning Extends Beyond You
Insurance planning is not only about protecting yourself. A gap in one family member’s coverage can eventually affect the entire family. Other areas to consider include:
- Aging parents: Do they have a plan for long-term care, powers of attorney, and future care decisions?
- Adult children starting their careers: Do they understand employer benefits, disability coverage, renters or homeowners insurance, auto liability limits, and the importance of auto liability limits, and the importance of protecting their income?
- A nonworking spouse or caregiver: If their household, childcare, or caregiving role had to be replaced, what would that cost?
- Business owners: Is there coverage for key people, buy-sell obligations, business overhead, liability risks, and succession needs?
Questions to Ask: If something happened to a parent, spouse, child, caregiver, or business partner, would the financial impact eventually reach me or my family? Are there conversations we should have now —before care, income, or business-continuity decisions become urgent?
When Was Your Last Insurance Review?
Insurance needs change as your income, family, home, business, and net worth evolve. An annual review can help determine whether your policies still reflect your current life and responsibilities.
At Wealth Avenue, we believe good planning means preparing for opportunities while protecting against the unexpected. If it has been a while since you reviewed your coverage, or discussed these issues with your parents or children, we would be happy to help you take a fresh look at how insurance fits into your family’s overall financial plan.
Your Team at Wealth Avenue,
P.S. Our greatest compliment is an introduction.
Insurance is often overlooked until a life change, or an unexpected event, reveals a gap. Many people are unsure whether their employer benefits are enough, whether their coverage will follow them to a new job, or whether their life, disability, long-term care, home, auto, and umbrella policies still reflect their current responsibilities.
If this newsletter brings someone to mind, an adult child beginning a career, a friend with a growing family, a fellow business owner, or someone concerned about aging parents, we would appreciate an introduction. We would be glad to serve as a resource and help them consider how insurance and risk management fit into their broader financial plan. A simple email introduction is all it takes.
One last read: The Wall Street Journal article below explores how families may use life insurance for more than income replacement. It discusses strategies for creating a legacy, providing estate liquidity, equalizing inheritances, supporting business succession, and enhancing charitable giving — along with the costs, risks, and importance of coordinating these decisions with financial, tax, and legal advisers.
**Important Disclosures:
This material is provided for general informational and educational purposes only. It is not intended to provide, and should not be relied upon as, personalized insurance, investment, legal, or tax advice. You should consult the appropriate qualified professional regarding your specific circumstances.
Insurance products are subject to terms, conditions, exclusions, limitations, underwriting approval, and the claims-paying ability of the issuing insurance company. Policy benefits, features, costs, riders, portability provisions, conversion options, premium requirements, and availability vary by policy, carrier, and state.
Income examples are hypothetical and are provided for illustrative purposes only. Actual earnings, employment duration, taxes, inflation, retirement plan contributions, employer matching contributions, pension accruals, and Social Security benefits will vary. Disability insurance generally replaces only a portion of income and may not fully replace lost wages or benefits.
Permanent life insurance may involve higher premiums, policy charges, surrender charges, investment or interest-crediting risk, and potential tax consequences. Loans and withdrawals may reduce policy cash value and death benefit, may cause the policy to lapse, and may result in taxable income.
Long-term care insurance benefits are paid only when policy conditions are met. Premiums may increase, and benefits may be limited by elimination periods, benefit caps, exclusions, inflation provisions, and other policy terms.
Wealth Avenue™ does not provide legal or tax advice. Any discussion of tax treatment is general in nature and may not apply to your individual situation. Consult your tax advisor, attorney, and licensed insurance professional before purchasing, replacing, modifying, or canceling any insurance policy.
Before replacing existing coverage, carefully compare benefits, costs, surrender charges, exclusions, underwriting requirements, and the potential loss of guarantees or favorable policy provisions. Replacement may not be appropriate in all circumstances.**