NEWSLETTER
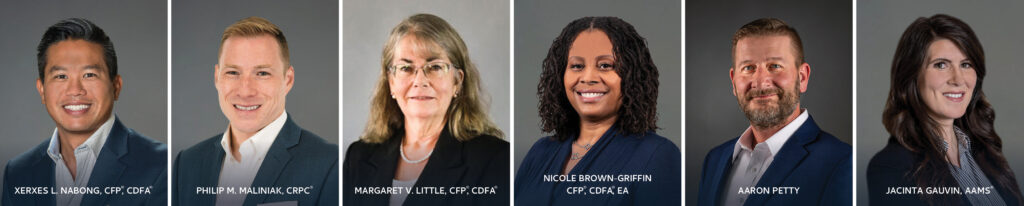
Xerxes Nabong, CFP®, CDFA®
Philip M. Maliniak, CRPC®
Nicole Brown-Griffin, CFP®, CDFA®, EA
Aaron Petty, Client Associate
Hampton Roads: (757) 394-3486
Greater Phoenix: (480) 687-9339
Orange County: (949) 660-8869
Wealth Avenue September 2026 Newsletter: Looking Ahead of the Midterm Elections: Earnings, Volatility, and the Path Forward
Prepared by Wealth Avenue using market insights from Scott Ladner, Chief Investment Officer, Horizon Investments. Source commentary dated August 20, 2026
A Note to You, Our Clients
As we move through the second half of 2026 and approach the midterm-election season, we wanted to share our perspective on the current market backdrop. Drawing on recent commentary from Scott Ladner, Chief Investment Officer at Horizon Investments, an investment partner we meet with quarterly to help inform our guidance and oversight of managed strategies, we are looking at the data behind this year’s market performance — particularly earnings growth, interest rates, capital spending, labor-market resilience, and the potential for election-related volatility.
The headline is straightforward: while risks remain, corporate earnings have been stronger than many investors may realize. That strength has helped markets absorb a number of macroeconomic headwinds.
Why Earnings Matter Right Now
The S&P 500 Index has advanced 13% year-to-date, but earnings are up approximately 25%. In the technology sector, stocks have risen roughly 25%, while tech earnings have grown about 50%.
That distinction is important. When markets rise sharply, it is natural to ask whether valuations have become stretched. But this year, earnings growth has outpaced stock-price gains. As a result, price-toearnings ratios are lower than they were at the beginning of the year.
Recent data continues to reinforce the importance of this earnings-versus-macro balance. Last week’s Personal Consumption Expenditures (PCE) report showed headline PCE rising 0.2% month over month and 3.7% year over year, while core PCE, which excludes food and energy, also rose 0.2% for the month and remained elevated at 3.3% year over year. That leaves inflation above the Federal Reserve’s long-term target and keeps the debate around future Fed policy active.
At the same time, recent technology earnings have continued to show strength, particularly in areas tied to artificial intelligence infrastructure and datacenter demand. Nvidia’s latest quarterly results more than doubled year-ago levels, supported by continued demand for GPUs and AI-related infrastructure. More broadly, large technology companies continue to invest heavily in AI buildouts, cloud infrastructure, and related applications. Investors are still rewarding earnings growth, but they are also becoming more focused on whether elevated capital spending can translate into durable returns.
Our view: The market’s strength has not been driven by price momentum alone. Earnings growth and company fundamentals have done much of the heavy lifting. Recent inflation data remains a policy headwind, but strong technology earnings and continued AI-related investment have helped support the broader earnings picture.
The Macro Wall That Has Not Stopped the Market
This has not been an easy macro environment. So far in 2026:
- The 2-year U.S. Treasury yield is about 75 basis points higher
- The 10-year U.S. Treasury yield is roughly 50 basis points higher.
- Oil prices are up approximately 50%.
- Gasoline is above $4 per gallon.
- The U.S. dollar has strengthened.
Any one of these could normally act as a headwind for stocks. Together, they create a challenging backdrop. Yet U.S. equities have still performed well, and international equities have also shown strength. That does not mean macro factors no longer matter. It means company-level fundamentals have been strong enough to offset a surprising amount of pressure.
Tailwinds We Are Watching
- Stronger Earnings Growth – The most important support for markets this year has been earnings. Companies have continued to report results that are better than the macro backdrop might suggest. Banks and retailers have pointed to a generally healthy consumer and economy, while technology earnings have remained especially strong.
- Broader Capital Spending – Capital expenditure is no longer only an artificial intelligence story. AI-related investment remains significant, but spending is also broadening into other sectors of the economy. That broadening is a positive medium-term signal because it suggests businesses are investing in productivity, capacity, and future growth.
- A More Resilient Labor Market – The much discussed wave of AI-related job losses has not materialized in the way many feared. Instead, AI and productivity gains appear to be contributing to new roles, new businesses, and new categories of work. There will still be disruption. However, the current data do not support a simple “AI up, jobs down” framework.
Headwinds We Are Monitoring
- Federal Reserve Uncertainty – The Federal Reserve has moved away from providing as much forward guidance. That shift is understandable, but markets still benefit from having a clear framework for how the Fed will approach its dual mandate of price stability and maximum employment. The issue is not uncertainty itself. Markets can handle uncertainty. The challenge is uncertainty around the Fed’s reaction function — how policymakers are likely to respond as inflation and employment data evolve. For now, the most likely path appears to be a steady one: the Fed remains patient unless incoming data require a change.
- Midterm-Election Volatility – Midtermelection years have historically brought more volatility during September and the first half of October, before markets begin to recover ahead of the actual elections. Seasonality is not a prediction, and history does not repeat perfectly. Still, as we approach the midterms, investors should be prepared for a potentially choppier stretch. For long-term investors, the key is to avoid letting short-term political noise overwhelm the underlying fundamentals.
- Geopolitical Risk – The ongoing conflict involving Iran remains a known risk. Markets have broadly indicated that the conflict has not materially changed the economic outlook, but geopolitical risk can still create short-term volatility, particularly if energy prices or supply routes are affected.
AI Capital Spending: Moving Into the “Prove It” Phase
The AI investment cycle is entering a new stage.
For the past several years, companies were often rewarded simply for spending aggressively on AI capacity. Now, investors are becoming more selective. Companies increasingly need to demonstrate that capital spending can lead to credible returns.
This does not mean the capital spending boom is ending. In fact, it appears to be broadening. But markets are no longer valuing every dollar of AIrelated spending equally.
For large technology companies, the strategic stakes remain high. Spending too little and falling behind in AI could be a major competitive risk. Spending too much may still be rational if the alternative is losing long-term relevance. The difference now is that investors want more evidence of return on investment.
What This Means for Investors
As we look ahead to the midterm elections, we expect the possibility of increased volatility. Higher interest rates, elevated energy prices, a stronger dollar, geopolitical uncertainty, and election-season dollar, geopolitical uncertainty, and election-season noise all remain relevant risks.
At the same time, the underlying earnings picture remains constructive. Earnings growth has outpaced stock-price gains, capital spending is broadening, productivity gains are spreading through the economy, and the labor market has been more adaptive than many expected.
This is a reminder that short-term volatility and longterm fundamentals are not the same thing. We continue to believe the most useful approach is to stay focused on data, diversification, and the role each investment plays within a broader financial plan.
Bottom Line
The central story of 2026 is not that investors are ignoring risk. It is that earnings and company fundamentals have been strong enough to carry markets through a difficult macro environment.
The midterm-election season may bring a choppier path in the near term. But for now, earnings remain the key variable to watch.
At Wealth Avenue, we are constantly watching these developments and evaluating how changing conditions may affect client portfolios and financial plans. We are prepared to make adjustments when warranted. If anything meaningful changes in your life or financial circumstances, or if you would like to revisit your plan in light of current market conditions, please contact us so we can determine whether a meeting would be appropriate.
Your Team at Wealth Avenue,
P.S. Our greatest compliment is an introduction.
Market updates and newsletters like this often lead to important conversations — not just about where the S&P 500 may go next, but about how earnings growth, artificial intelligence, interest rates, inflation, and election-year volatility may affect a family’s broader financial picture.
These are the conversations we are having with clients every day. We are constantly watching market developments, working with our outside investment CIO team, and evaluating how opportunities like AIrelated innovation may fit within a disciplined, diversified portfolio strategy.
Earnings, labor markets, geopolitical tensions, artificial intelligence, and technology all play an important role in how we evaluate and guide investment management strategies on your behalf. Still, no single theme replaces the importance of thoughtful planning, disciplined risk management, and a portfolio built around your goals, time horizon, and financial circumstances.
If someone you know is asking questions after reading market commentary like this — whether they are wondering about AI exposure, concerned about volatility ahead of the midterm elections, or simply unsure whether their portfolio is still aligned with their goals — we would be glad to be a resource.
An introduction is always appreciated, and we would welcome the opportunity to help them think through today’s market environment with discipline, context, and a planning-first perspective. To those of you who continue to introduce us to family, friends, and coworkers, THANK YOU. We deeply appreciate the trust and confidence you have placed in us.
One last read: A recent Forbes article highlighted the views of Dr. Edward Yardeni, a veteran Wall Street economist, investment strategist, and president of Yardeni Research. Yardeni is widely known for his longrunning focus on U.S. corporate resilience, productivity growth, and market-cycle analysis. In the article, Yardeni assigns an 80% probability to the current technology-driven bull market extending into the early 2030s, supported by the potential for artificial intelligence to improve corporate productivity. Under his base-case scenario, the S&P 500 could reach 10,000 by the end of 2029, assuming an annualized growth rate near its long-term historical average of roughly 7%. While forecasts are never guaranteed, his perspective reinforces one of the more positive themes for markets today: if AI driven productivity gains continue to support earnings growth, corporate fundamentals may remain an important offset to macroeconomic uncertainty.
**Important Disclosures:
NOT GUARANTEED | CLIENTS MAY LOSE MONEY | PAST PERFORMANCE NOT INDICATIVE OF FUTURE RESULTS
This material is provided for informational and educational purposes only and should not be construed as individualized investment advice, a recommendation, or a solicitation to buy or sell any security. The views expressed are based on current market conditions and are subject to change without notice.
Past performance is not indicative of future results. The commentary in this report is not a complete analysis of every material fact with respect to any company, industry, or security. Opinions referenced are as of the date of publication and may not necessarily come to pass. Forward-looking statements cannot be guaranteed. Information obtained from third-party sources is believed reliable, but accuracy and completeness cannot be guaranteed.
The S&P 500 or Standard & Poor’s 500 Index is a market-capitalization-weighted index of 500 large U.S. publicly traded companies. References to indices, or other measures of relative market performance over a specified period of time, are provided for informational purposes only. Reference to an index does not imply that any account will achieve returns, volatility, or other results similar to that index. Indices are unmanaged and do not have fees or expense charges, both of which would lower returns. Individuals cannot invest directly in any index.
Investing involves risk, including the possible loss of principal. There can be economic times when all investments are unfavorable and depreciate in value.
Clients may lose money.
Wealth Avenue is not affiliated with Horizon Investments. Horizon Investments is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. Horizon Investments is a registered trademark of Horizon Investments, LLC.
Source: Horizon Investments, “Straight from Scott: Mid-Quarter Commentary,” Scott Ladner, Chief Investment Officer, August 20, 2026. © 2026 Horizon Investments, LLC. H90052 0826.**